To reconcile a business loan in Xero, keep the loan in its own liability account, then split every repayment into capital, interest and fees using the lender’s statement, and finish by agreeing the Xero balance to the lender’s closing balance. Capital repayments reduce what you owe and are not an ordinary business expense. Only the interest and fees belong in your Profit and Loss report.
This guide shows how I work through a loan for a small business, step by step. It includes a fictional example with a difference I find and trace, so you can see what an error looks like and how it gets fixed. I’m Chris, an AAT Licensed Accountant based in Hildenborough near Tonbridge, and I do this for sole traders, landlords, limited companies and CICs across Kent and remotely across the UK.
TL;DR
- Give every loan its own liability account in Xero, so the balance can always be compared with the lender’s figure.
- Reconcile the money you receive to that liability account, never to income.
- Split each repayment into capital (liability), interest (expense) and fees (bank charges) using the lender’s statement.
- Capital repayments are not a business expense. Coding the whole payment as an expense overstates costs and leaves the balance sheet wrong.
- At year end, agree the Xero loan balance to the lender’s statement and investigate any difference before posting a journal.
Table of Contents
- Why loans trip people up
- What a reconciled loan looks like
- Step 1: Set up the loan account properly
- Step 2: Get the opening balance right
- Step 3: Reconcile the loan advance
- Step 4: Split every repayment
- Why capital repayments are not an expense
- Step 5: Reconcile interest charges and lender fees
- A fictional example: finding a £1,020 difference
- Step 6: The year-end loan checklist
- Common mistakes I look for
- How this fits into everyday reconciliation
- Getting help with your loan reconciliation
- FAQ
- Need help?
- Sources
Why loans trip people up
A bank loan looks simple. Money arrives, then a fixed amount leaves every month. The trouble is that the monthly amount is never one thing. It is usually capital (paying back what you borrowed), interest (the cost of borrowing) and sometimes a fee, all wearing one amount.
A guide on loan repayments in Xero explains the effect well. Interest is a cost of borrowing and belongs on the Profit and Loss report. Capital only reduces a liability on the balance sheet and never appears in the Profit and Loss. That is why a business can see its bank balance fall while its profit looks healthy.
Xero’s own UK guide to recording transactions, published in June 2026, lists loan payments among the transactions that benefit from an accountant or bookkeeper’s input, because they have to be split between capital and interest and followed through a schedule.
If your repayments look “fine” in the bank feed but your accounts never quite agree with the lender, this is usually where the gap sits.
What a reconciled loan looks like
Before the steps, here is the end result I aim for with any loan:
- One liability account per loan, named after the lender.
- An opening balance that agrees with the lender’s statement on the day your Xero records start.
- The advance recorded as a liability, not income.
- Each repayment split into capital, interest and fees.
- A year-end loan balance in Xero that matches the lender’s statement, or a short note explaining the difference.
Everything below is a way of reaching those five points calmly, without a last-minute mess at year end.
Step 1: Set up the loan account properly
In Xero, the loan lives in your Chart of Accounts. The usual route is Accounting, then Chart of Accounts, then Add Account. The account type matters:
- Non-current liability for a loan that runs for more than a year.
- Current liability for a short-term facility or an overdraft-style arrangement.
These choices follow the ReportPilot guide, which also suggests naming the account after the lender and setting the tax rate to No VAT in the UK, because loan capital and interest are outside the scope of VAT. The same guide cites the advice of giving each loan its own code, for example a sub-code beneath the main loan code, so each balance can be monitored separately.
An older Xero developer guide takes the same line: a separate liability account for the money borrowed and the capital repaid, and a separate expense account for interest. It also notes that a loan is classed as current if it is repaid within the current financial year and long-term if it spans several.
Two habits save me the most time later:
- One account per loan. If you have a bank loan and a director’s loan, or two bank loans, never share an account. Blending them makes the lender’s statement impossible to agree.
- Keep your chart of accounts lean. A loan account does not need five sub-accounts. If you want help deciding which accounts you need, my guide to setting up a Xero chart of accounts properly and the one on keeping it to 30 to 50 accounts cover this.
Step 2: Get the opening balance right
If the loan was already running when you started using Xero, the first job is the opening balance. This is the amount you still owed on the day your Xero records begin, and it must come from the lender’s statement for that date, not from memory or from your last set of accounts alone.
When I take on a loan like this, I ask for:
- the lender’s statement showing the balance on your conversion date;
- the original loan agreement, showing the amount, term and any fees;
- the last set of accounts or the previous bookkeeper’s closing figures, to compare.
If the statement and the old accounts disagree, I resolve that before going further. An error in the opening balance is carried into every later month. It is one of the commonly cited reasons a balance will not reconcile, along with an error in an earlier reconciliation, as listed in the RoyceIQ guide.
I cover opening balances in more detail in Opening Balances in Xero and Day One Opening Balances, so I won’t repeat the whole process here. For a loan, the one thing to remember is that the opening figure is a liability and should match the lender’s own number.
Step 3: Reconcile the loan advance
When the lender pays the money into your business bank account, it appears as a deposit in your bank feed. The loan is a debt, so the money received is not income. In the reconcile screen, I use the Create option (Receive Money), and code the line to the loan liability account, not to sales or other income, as the ReportPilot guide describes.
If you code a loan advance to income by mistake, your profit looks better than it is, and the tax you calculate on it will be wrong too. For a sole trader that flows into Self Assessment. For a limited company it flows into Corporation Tax.
When the lender pays a supplier directly
Some lending, such as asset finance, never touches your bank account. The lender pays the supplier and you repay the lender. In that case nothing arrives in the feed, so there is nothing to reconcile. A manual journal is needed to record the asset and the matching loan liability. The same guide says to ask your accountant for this journal, and it is one of the cases where I would rather you sent me the paperwork than guessed.
When fees are taken from the advance
Lenders sometimes deduct an arrangement fee before paying you. The bank deposit is then smaller than the loan. I record the full amount borrowed as the liability and the fee separately as a cost, so the loan account starts at the true amount owed. Otherwise the Xero loan balance will sit below the lender’s figure from day one.
Step 4: Split every repayment
This is the step that matters most. For each repayment line in the bank feed, the method described in the RoyceIQ guide is:
- Open the Create tab on the bank line.
- Set the contact to the lender.
- Add a capital line coded to the loan liability account.
- Add an interest line coded to an interest expense account.
- Add a fee line, if there is one, coded to bank fees.
- Check that the lines add up to the amount that left your bank.
The amounts come from the lender’s statement or repayment schedule, not from an estimate. If the statement is not available yet, the same guide suggests coding the whole payment to the loan account for now and posting a journal later that moves the interest to Interest Expense. I use that as a stopgap only, and I mark the transactions so they are not forgotten.
Why the split changes
On a typical repayment loan, interest is higher at the start, because you owe more, and falls as the balance falls. So the capital and interest split is different from month to month even if the payment stays the same. The RoyceIQ guide warns against reusing one split month after month unless the lender confirms the split is fixed. I agree, and I check it against the schedule.
If the schedule is predictable, the Xero developer guide suggests preparing scheduled payments or bills with separate capital and interest lines. If it is not, you create the payments as they happen. For most of the small businesses I work with, reconciling from the monthly statement is straightforward enough.
Why capital repayments are not an expense
This is the question I am asked most. If the money left your account, why isn’t it a cost?
Because repaying capital is giving back something you borrowed. You are not paying for something that earned income. You are reducing a debt. The accounting effect is that the bank goes down and the liability goes down by the same amount, so your profit does not move at all.
Interest is different. It is the price of having the money, so it is a cost of the business, and it belongs on the Profit and Loss. Interest on a genuine business loan is generally an allowable cost, though I check the circumstances of each business, particularly where a loan was used partly for private purposes.
The damage from coding the whole repayment to an expense is twofold:
- Profit is understated. Expenses look too high, so profit looks lower than it truly is.
- The balance sheet is wrong. The loan balance never falls, so your accounts show you owing more than you do.
The ReportPilot example (in US dollars) shows the same pattern: the whole payment in expenses inflates costs, leaves the balance sheet showing the wrong amount owed and, on a tax return, claims capital that is not deductible. The fix is to reverse the split at year end. The principle is exactly the same in sterling.
For limited companies the point matters for the Corporation Tax computation, and my guide to Corporation Tax for UK limited companies explains how profit feeds into the tax bill.
Step 5: Reconcile interest charges and lender fees
Interest and fees can arrive in three ways:
- Inside the monthly repayment. This is the standard setup. The split above deals with it.
- As a separate debit. Some lenders charge interest or fees on their own line. Code them to the interest or bank fees account, not to the loan.
- Added to the balance. Some facilities add interest to what you owe instead of taking it from your bank. Nothing appears in the feed, so a journal is needed to debit interest and credit the loan.
The last one is the quiet cause of many loan differences. The Xero balance looks right according to the bank feed, but the lender’s balance is higher, because interest has been charged to the loan and your books have never recorded it.
A fictional example: finding a £1,020 difference
This is an invented example to show my method. It is not a real client.
A small limited company, Oakfield Joinery Ltd, borrows £24,000 on 1 April. The lender deducts a £240 arrangement fee, so £23,760 arrives in the bank. The company repays £1,100 a month. Six months later, I am preparing the half-year figures.
The lender’s statement shows:
| Item | Amount |
|---|---|
| Amount borrowed | £24,000 |
| Arrangement fee | £240 |
| Six repayments of £1,100 | £6,600 |
| Interest included in those repayments | £780 |
| Capital repaid (£6,600 minus £780) | £5,820 |
| Lender’s closing balance (£24,000 minus £5,820) | £18,180 |
The previous month’s bookkeeping, done quickly, coded the £23,760 deposit and all six repayments to the loan account. Here is what Xero shows:
| Xero loan account | Amount |
|---|---|
| Received (credit) | £23,760 |
| Repayments (debit) | £6,600 |
| Balance | £17,160 |
The lender says £18,180. Xero says £17,160. The difference is £1,020, and Xero is lower, so I know the books owe less than the lender says.
How I investigate it
First, I check the direction. A lower Xero balance points to charges that the lender has added to the loan but my books have not recorded. The RoyceIQ guide gives the same direction of travel: a lower Xero balance suggests interest has been missed, while a higher one suggests interest was coded to the loan.
Second, I look for the obvious number. The interest on the statement is £780. If the difference were £780, I would be done. It is £1,020, so something else is going on.
Third, I subtract. £1,020 minus £780 leaves £240. That is exactly the arrangement fee the lender took from the advance. The deposit was coded in full as £23,760, so the loan account started £240 short.
Fourth, I confirm before posting. Both pieces are traceable to the statement and the loan agreement. A difference I can’t explain stays unposted, because a journal that just forces the balance to agree would hide a real error.
The correction
I post one journal:
| Account | Debit | Credit |
|---|---|---|
| Interest expense | £780 | |
| Bank fees (arrangement fee) | £240 | |
| Loan account | £1,020 |
The loan account then reads £18,180, which agrees with the lender. The Profit and Loss now carries £780 of interest and the fee, and the capital repayments of £5,820 sit only on the balance sheet. For a limited company, the treatment of a larger arrangement fee can differ from a small one, so I decide that case by case.
From then on the monthly repayments are split properly, so the same difference does not reappear.
Step 6: The year-end loan checklist
At year end, I work through the loan in a fixed order:
- Get the lender’s year-end statement for the accounting year end date, showing the closing balance, interest charged and fees.
- Compare the Xero loan account on the balance sheet with that closing balance.
- Compare the interest and fees in the Profit and Loss with the statement totals.
- Investigate any difference by direction, then by amount, as in the example above.
- Post a journal only when the cause is known, and keep the statement with the working papers.
- Split the balance between what falls due within a year and what falls due later, so it is shown correctly in the accounts.
The last point matters for limited companies, where the accounts show amounts due within one year separately from those due later. The Xero developer guide describes the same current and long-term split.
Lenders often issue annual statements some weeks after the year end. If you are waiting for one, tell me early and I will plan the accounts around it rather than rushing the figures.
Common mistakes I look for
- Advance coded to income. Profit and tax are overstated.
- Whole repayment coded to an expense. Costs look too high and the loan never reduces.
- Whole repayment coded to the loan. Interest vanishes from the Profit and Loss.
- A copied split. The same capital and interest figures repeated each month, even though the real split shifts.
- Loans sharing one account. A bank loan and a director’s loan mixed together.
- Wrong opening balance. Taken from the old accounts, not the lender.
- Fees ignored. Arrangement or early repayment charges left sitting in the loan account.
If you recognise two or more of these, my article on signs your bookkeeping needs professional help may feel familiar.
How this fits into everyday reconciliation
Loan reconciliation is one part of a wider routine. When the bank feed is matched regularly, the loan lines are easy to spot and split while the lender’s statement is fresh. My guide to bank reconciliation in Xero covers that routine, and my bookkeeping clean-up checklist shows how I tidy up when several months have been left.
For landlords, the same thinking applies to buy-to-let mortgages and property loans. The capital stays on the balance sheet, and the interest is dealt with in the rental figures, so the split must be clear before tax is calculated. If you are in that position, my rental reporting and bookkeeping service is built around it.
My view on loans in Xero
I find loans are rarely the problem on day one. The trouble starts a few months later, when a repayment has been coded in a hurry and nobody notices until the year-end statement does not agree.
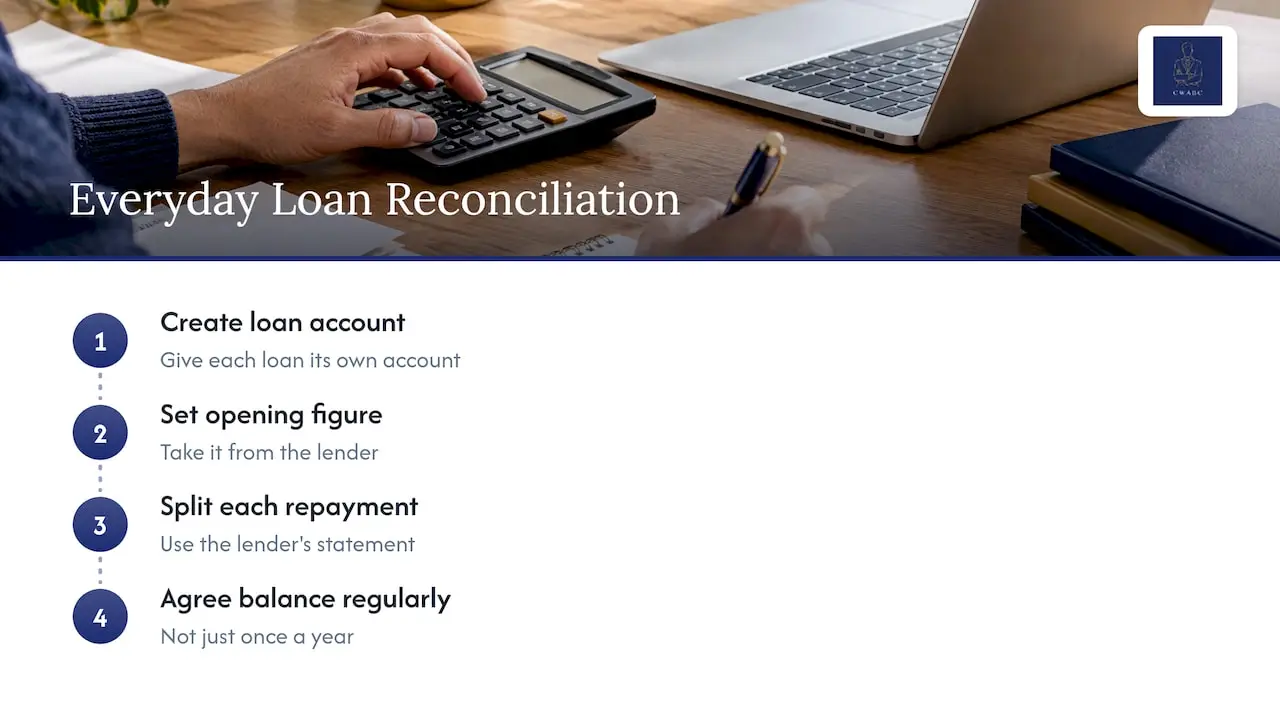
My approach is deliberately plain. I give each loan its own account, take the opening figure from the lender, split every repayment from the statement, and agree the balance regularly instead of once a year. That way a small difference is a five-minute query, not a rebuilt year.
I work directly with every client, so the person who sets up your loan account is the person who reconciles it and explains it to you in everyday language. I use cloud software such as Xero, QuickBooks and FreeAgent and a paperless routine, so the lender’s statements, agreements and my working notes sit together and are ready for HMRC when needed.
If you would rather hand the loan to someone who does this routinely, that is what I am here for.
Chris
Getting help with your loan reconciliation
If your loan balance in Xero does not agree with the lender, or you are unsure how past repayments were coded, I can review the account, trace the difference and set up a routine so it stays right. This sits within my bookkeeping services, alongside Self Assessment, VAT, payroll, Corporation Tax and Making Tax Digital support. Pricing is agreed clearly upfront and tailored to what you need.
If you are a limited company, I can also make sure the loan carries through correctly to your annual accounts and Corporation Tax. You can see the full range on my accounting services page.
FAQ
Should loan repayments go through the Profit and Loss?
Only the interest and any fees should. The capital part reduces the loan liability on the balance sheet and never appears in the Profit and Loss. Coding the whole payment to an expense overstates your costs and leaves the loan balance too high.
What if I do not have the lender’s statement yet?
One approach is to code the whole repayment to the loan account for now, then post a journal later to move the interest to Interest Expense once the statement arrives, as the RoyceIQ guide describes. I treat this as temporary and flag those transactions so they are corrected before the accounts are finalised.
Why is my Xero loan balance different from the lender’s?
The usual causes are interest or fees that were never recorded, interest coded to the loan by mistake, or a wrong opening balance. A lower Xero balance often points to missed charges, and a higher one often points to interest coded to the loan. Work out the cause first, then post a journal for the difference.
Do I need a separate account for each loan?
Yes, it makes life much easier. A separate account, or sub-code, for each loan lets you compare each balance with its own lender statement, and it avoids mixing a bank loan with a director’s loan.
Can you help if my loan was set up wrongly in the past?
Yes. I can review the loan account against the lender’s statements, correct the coding and set the routine going forward. Get in touch with the details of the loan and the software you use.
Need help?
If you would like a second pair of eyes on your loan reconciliation in Xero, or want it set up properly from the start, please contact me here. I will look at your situation and explain the next steps in plain English.
Sources
- Loan repayments in Xero: why they’re not on the P&L
- How to Record Loan Repayments in Xero Correctly
- How to record accounting transactions for your small business (Xero UK)
- The developer’s guide to lending in Xero
Recommended
- Finish Xero bank reconciliation in a day with AAT bookkeeper shortcuts
- Opening Balances in Xero: How to Set Up Your Accounts Correctly
- How to Reconcile VAT Returns to Your Bookkeeping Records
- How to reconcile your sole trader bank account
This article provides general information based on UK tax and accounting rules at the time of publication. It is not a substitute for advice tailored to your individual circumstances. Tax legislation and HMRC guidance may change. If you need advice about your specific situation, please contact me at CW Licensed Bookkeeper & Accountant.