Repairs restore an existing asset and are normally deductible against rental income in the year you pay for them. Capital improvements alter or enhance the property beyond its original condition, so they sit outside your rental accounts and instead feed into Capital Gains Tax when you eventually sell. HMRC decides which is which by looking at the facts of the work, not the wording on your invoice. The sections below use HMRC’s own examples to show exactly where that line falls.
TL;DR:
- Replacing a roof or rewiring that restores the original capacity is generally a repair, while structural changes or additions like extensions are capital improvements.
- Small repairs like fixing storm damage or swapping out existing kitchen units are deductible in the same year, but enlarging a kitchen or building a new bathroom counts as a capital expense.
- For mixed projects, landlords should obtain itemized invoices and proportion costs based on the work scope to avoid misclassifying expenses.
- Expenses incurred immediately after buying a property that bring it to a lettable state are often deemed enhancements, not repairs, affecting future Capital Gains Tax calculations.
- Keeping before-and-after photos, contractor scopes, and detailed records from the start simplifies correct classification and supports tax claims during HMRC audits.
Table of Contents
- HMRC’s practical test: the ‘entirety’ and what to look for
- Kitchens, roofs, rewiring and extensions: what usually counts
- Replacing domestic items: a separate relief entirely
- Works after purchase: buying a property in poor condition
- Apportioning mixed projects and briefing your contractor
- Tax consequences and the records that back them up
- Practical steps I recommend for your bookkeeping
- Common mistakes I see landlords make
- How I can help with repairs, improvements and rental tax
- Sources
- FAQ
- Need help?
HMRC’s practical test: the ‘entirety’ and what to look for
HMRC does not ask what your builder called the job. It asks what asset existed before the work and what existed afterwards, and whether replacing a part restored the property or created something better than what was there. This is often called the “entirety” test, and it comes straight from HMRC’s guidance on repairs versus capital expenditure: if the work goes beyond restoring the property to its earlier condition, it’s capital, regardless of the invoice description, the cost, or how big the job feels to you.
The distinction usually turns on whether you replaced a subsidiary part of an asset or the entirety of it. Swap a broken guttering section for new guttering and you’ve repaired the roof. Replace the whole roof structure and add a room in the process, and you’ve created something new. HMRC’s business income manual confirms that using modern equivalent materials, uPVC windows instead of timber, for example, doesn’t automatically tip a repair into capital territory, provided the function stays the same.
Indicators that tend to point towards capital treatment include:
- Extending the floor area or adding a storey
- Reconstructing a substantial part of the building rather than a component
- Work that materially increases the property’s value beyond simple upkeep
- Converting a house into flats, or vice versa
None of this depends on cost alone. A £15,000 repair bill for a full rewire after storm damage can still be revenue expenditure, while a £3,000 job that changes the layout of a kitchen might be capital.
Kitchens, roofs, rewiring and extensions: what usually counts
Real examples make this far easier to apply than the legal test alone. Here’s how the four most common landlord projects tend to be treated, based on HMRC’s own guidance.
- Kitchen refits. Swapping out cracked worktops, tired cabinet doors, and a failing oven for equivalent units is a repair. Extend the kitchen into a former pantry, knock through a wall, or add a breakfast bar where there wasn’t one, and you’ve improved the asset rather than restored it. The dividing line is whether the room’s function and layout stayed the same.
- Roof work. Replacing storm damaged tiles, slates, flashing or guttering is revenue expenditure under HMRC’s definition of a repair. Rebuilding the roof structure to raise the ridge height, or adding a loft conversion underneath it, is capital.
- Rewiring. A full rewire that restores the property’s existing electrical capacity, replacing an unsafe or worn out system with a modern equivalent, is usually a repair. Rewiring to support a significant capacity increase (say, for an extension or a change of use) tends to be capital.
- Extensions and structural alterations. These are capital in almost every case, because you’re adding to the asset rather than restoring what was already there.
Pro Tip: Keep before-and-after photographs of every major job. HMRC’s own guidance treats the physical evidence of what existed before the work as often decisive when a classification is questioned.
Borderline cases are common, and the right answer nearly always rests on the specific facts of your project rather than a general rule of thumb.
Replacing domestic items: a separate relief entirely
Furnished lettings have their own rule, distinct from the repair-versus-capital question above. Replacement of domestic items relief lets you deduct the cost of replacing an item used by the tenant, a fridge, a sofa, carpets, curtains, when the old one wears out.
Three points matter here:
- The deduction is generally capped at the cost of an equivalent replacement. Upgrade from a basic washing machine to a premium model and only the cost of the equivalent basic machine is deductible under HMRC’s replacement domestic items guidance.
- This relief only applies to replacements. Furnishing a property for the first time doesn’t qualify, since there’s no old item being replaced.
- Incidental costs, such as delivery or removing the old item, can usually be included, and any proceeds from selling the old item reduce the amount you can claim.
This sits alongside, rather than instead of, the repairs test covered above.
Works after purchase: buying a property in poor condition
Landlords who buy a run-down property and immediately start work often assume the cost is a straightforward repair deduction. It usually isn’t. HMRC’s Capital Gains manual treats expenditure that brings a newly acquired property up to a lettable standard as putting it into a fit state for use, which is generally enhancement expenditure rather than a repair, even if the work looks identical to routine maintenance elsewhere.
That means the cost may be excluded from your rental income deductions, but it could later count when calculating Capital Gains Tax on disposal, under the rules in TCGA92/S38. To support that claim years down the line, retain:
- The property survey from before or shortly after purchase
- Dated photographs showing the condition on acquisition
- Correspondence with your solicitor or surveyor referencing defects
Apportioning mixed projects and briefing your contractor
Most substantial jobs mix genuine repair with capital improvement, and HMRC expects you to apportion the cost on a reasonable, evidenced basis rather than picking whichever label suits your tax return.
- Ask your contractor for a scope of works that separates repair items from fittings and from structural changes before the job starts.
- Request an itemised invoice that mirrors that scope, so each line can be matched to a category later.
- Apportion shared costs (scaffolding, skip hire) proportionally across the repair and capital elements using floor area, time spent, or the contractor’s own cost breakdown, whichever is most defensible.
Pro Tip: If a contractor’s invoice simply says “kitchen renovation, £18,000” with no breakdown, go back and ask for one. A single undivided figure is the single biggest reason apportionment claims get challenged.
HMRC’s guidance on repairs and renewals is explicit on the risk here: if the true nature of the project is an improvement dressed up as several small repairs, the entire cost can be treated as capital, not just the improvement element.
Tax consequences and the records that back them up
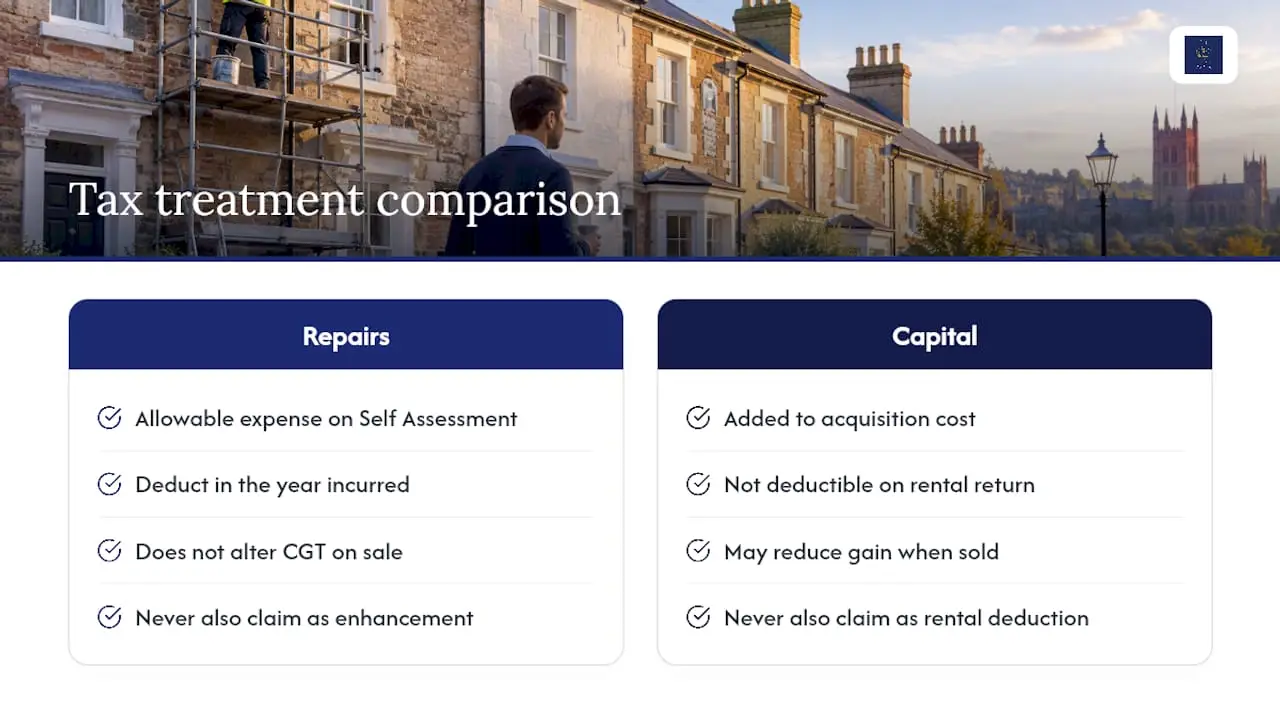
Repairs reduce your taxable rental profit in the year you incur the cost, appearing as an allowable expense on your Self Assessment return. Capital improvements don’t touch that computation at all. Instead, they’re added to your acquisition cost and may reduce your gain when you eventually sell, subject to the enhancement expenditure rules under TCGA92/S38. GOV.UK’s guidance on renting out a property confirms upkeep and repairs are allowable expenses, while renovation-level capital costs are excluded from the same computation.
One mistake catches landlords out repeatedly: claiming the same cost twice, once as a rental deduction and again as CGT enhancement expenditure. It’s one or the other, never both, and getting it wrong on your Self Assessment return can trigger an HMRC enquiry into your wider rental accounts.
What to keep on file: dated photographs before and after works, building surveys, planning or building-control approvals, itemised contractor invoices with VAT treatment noted, tenant correspondence about defects, and receipts for any items disposed of during the project.
Good records don’t just protect you at Self Assessment time. They’re often what makes a CGT enhancement claim stand up years later, when memories have faded and the contractor has long since moved on. My guide to rental income tax covers how these deductions flow through your annual return in more detail, and my piece on landlord Capital Gains Tax explains the enhancement expenditure side.
Practical steps I recommend for your bookkeeping
Getting the classification right at the point you pay the invoice saves a lot of unpicking later. I recommend landlords build this into their bookkeeping routine from day one rather than trying to reconstruct it at year end.
- Ask contractors for scopes that separate repair, fittings, and structural work before the invoice arrives, not after.
- Run two linked schedules: one for revenue repairs and replacement domestic items relief, one for capital improvements and acquisition enhancement costs. Record date, property, supplier, VAT treatment, amount, allocation, and a reference to your supporting evidence for each entry.
- Get an accountant involved before a large project starts, not after it’s finished, particularly for post-purchase works or any job where the repair/capital split isn’t obvious.
Pro Tip: Set these two schedules up in your bookkeeping software from the start of the tax year. Retrofitting them after twelve months of invoices is far harder than logging each one as it lands. My landlord bookkeeping guide sets out the fields I use for this in more detail.
Common mistakes I see landlords make
The recurring error is trusting the contractor’s invoice description instead of the facts of the work. A close second: no evidence of the property’s condition at purchase, which makes a later CGT enhancement claim almost impossible to support. Clear bookkeeping and an early conversation with an adviser prevent both.
— Chris
How I can help with repairs, improvements and rental tax
Sorting repairs from capital improvements is straightforward in theory and genuinely fiddly in practice, especially once invoices start mixing the two. CWABC is the alternative to guessing your way through a Self Assessment return: I work directly with landlords across Tonbridge, Sevenoaks and Kent, and remotely across the UK, on exactly this kind of classification, using paperless, cloud-based records in Xero, QuickBooks or FreeAgent so every repair and improvement is logged with evidence attached from day one.
My services for landlords include rental reporting and bookkeeping, Self Assessment Tax Returns from £250 one off, and Capital Gains Tax support for when you come to sell. If you’re mid-renovation, or you’ve just bought a property that needs work and you’re unsure how the costs should be treated, get in touch before the invoices pile up rather than after your tax return is due. You can also compare notes on the operational side of managing a rental with this property management guide.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What is the difference between capital improvements and repairs?
A repair restores an existing asset to its previous condition and is normally deductible against rental income in the year you pay for it. A capital improvement alters or enhances the asset beyond its earlier state, and its cost sits outside your rental accounts, feeding into Capital Gains Tax instead when you sell.
Is a new bathroom a capital improvement?
It depends on the facts. Replacing an old bathroom suite with an equivalent one is a repair, but adding a new bathroom where none existed, or extending the property to fit one, is capital because you’ve enhanced the asset rather than restored it.
What is the difference between repairs, maintenance and capital improvements?
Repairs and routine maintenance both restore or preserve an existing asset and are deductible against rental income. Capital improvements change or upgrade the asset beyond its original specification and are excluded from that deduction, appearing instead in your Capital Gains Tax computation on disposal.
What qualifies as a capital improvement?
Extensions, loft conversions, converting a house into flats, and structural alterations that increase floor area or value all typically qualify as capital under HMRC’s guidance. The test is whether the work created something different from what existed before, not simply how much it cost.
Can CWABC help me classify a specific project?
Yes. I work with landlords on exactly this kind of classification as part of my Self Assessment and bookkeeping services, using contractor scopes and itemised invoices to support the split between repair and capital costs.
Need help?
If you’re weighing up a renovation, dealing with a property bought in poor condition, or simply want your rental bookkeeping set up to survive an HMRC enquiry, get in touch and I’ll talk you through the practical steps.