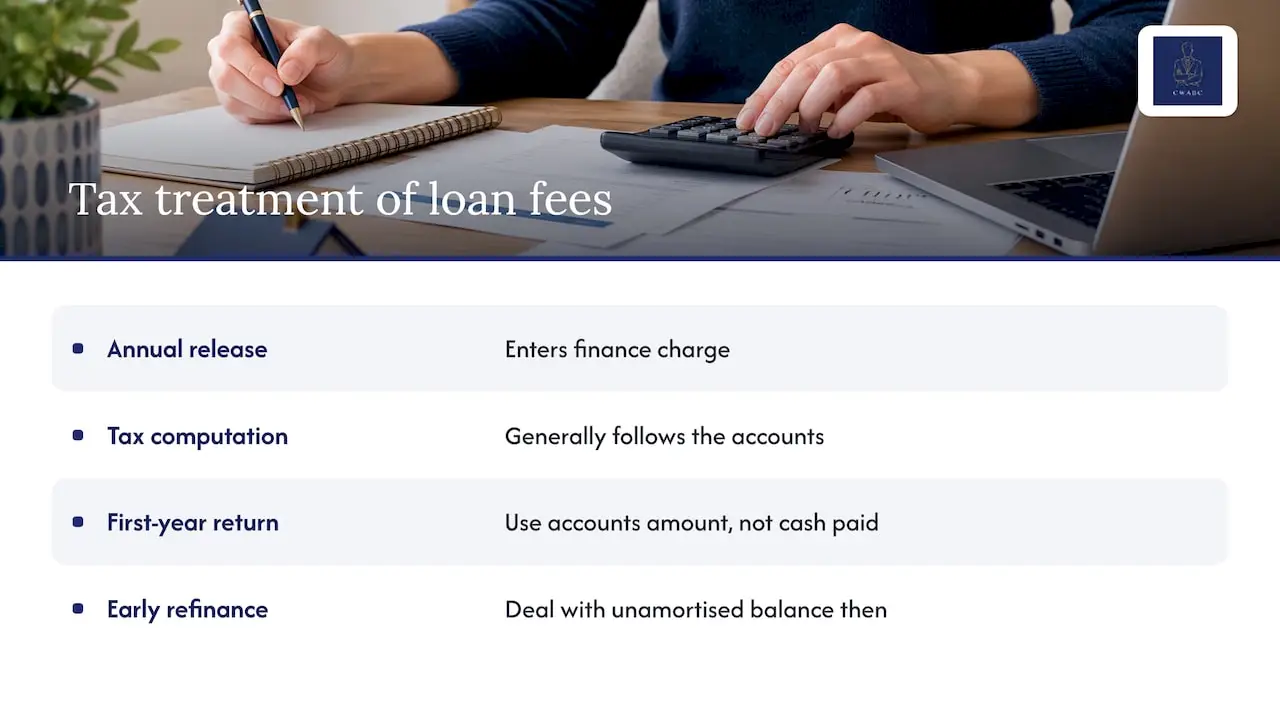
When a property company takes out a mortgage, the lender’s arrangement fee, the broker’s fee and the valuation cost are usually treated as costs of the loan. They are not treated as running costs of the rental business. In the accounts they are often spread over the life of the loan rather than charged all at once. For Corporation Tax, the company’s loan relationship rules then decide when the deduction is given. In practice that usually follows the accounts.
I’m Chris White, and this guide explains how I deal with these costs for property investment companies. It covers what goes where, a worked example with made-up numbers, and what I check in the paperwork. It does not repeat the general rules on mortgage interest. My guide to the mortgage interest tax credit covers that for individual landlords.
TL;DR
- Arrangement fees, broker fees and lender valuation fees are costs of getting the loan. They are usually dealt with together, not posted to “repairs” or “professional fees”.
- The accounting treatment (how the cost appears in your accounts) and the Corporation Tax treatment (when HMRC lets you deduct it) are two questions. In a company they are closely linked, but I answer them separately.
- Where the fee is a cost of the loan, it is often spread over the loan term. How much you spread depends on your accounting framework and on how big the fee is.
- A company’s loan costs fall under the loan relationship rules. An individual landlord’s fall under the property income rules. The two are not the same.
- Keep the offer, the completion statement and the lender’s redemption or balance statements. They are the evidence I need to get the numbers right.
Table of Contents
- Which costs I treat as costs of the mortgage
- How much these fees can be
- Accounting treatment and Corporation Tax are two questions
- When a fee needs spreading over the loan term
- A worked example: Harbour Lane Properties Ltd
- Paying upfront or adding the fee to the mortgage
- Company or individual: the rules are different
- If the mortgage never completes
- How I review mortgage agreements, completion statements and loan balances
- Common mistakes I see
- My own view on loan costs
- How I can help with your property company’s records
- FAQ
- Need help?
- Sources
Which costs I treat as costs of the mortgage
A mortgage rarely arrives with one neat charge. A typical purchase or refinance for a property company produces several, and they do not all belong in the same place.
| Cost | What it usually is | Where I normally start |
|---|---|---|
| Lender arrangement or product fee | A fee for arranging the mortgage, often a percentage of the loan | Cost of the loan |
| Broker fee | Paid to an adviser for finding and arranging the mortgage | Cost of the loan, once I have checked what it covers |
| Lender’s valuation fee | The lender’s own valuation of the security | Cost of the loan |
| Lender’s legal fees for the security | Legal work to register the charge | Cost of the loan, if it relates to the borrowing |
| Your own survey or purchase legal fees | Work for the buyer on the property itself | Usually part of the property’s cost, not the loan |
| Early repayment charge on an old loan | A penalty for leaving a deal early | Considered separately on a refinance |
The split matters because the two groups follow different rules. Costs of buying the property usually go into the cost of the property. They matter later for capital gains or a sale. Costs of arranging the borrowing belong with the loan.
A mortgage arrangement fee is a fee a lender may charge for arranging the mortgage, and NatWest explains that it can sometimes be added to the mortgage amount, in which case interest is payable on it. For one residential property investment loan, NatWest says the arrangement fee is taken on the day of drawdown. That timing matters, because it tells me which date the cost belongs to.
How much these fees can be
Fees for company buy-to-let borrowing vary a lot, so the amount affects how I treat the cost. A fee of a few hundred pounds is easy to deal with. A fee of several thousand needs more thought.
Some current examples from lenders themselves:
- Nationwide’s announcement for The Mortgage Works’ limited company range lists products with fees of two per cent, five per cent or £1,495, plus an existing-customer option with no fee.
- Atom bank’s commercial mortgage price list, effective from 8 June 2026, says its arrangement fee is calculated as a percentage of the loan and added to the total loan amount. It gives an example rate of 2.00%. The same list explains that part of the fee may be paid to an intermediary as a procuration fee.
A Guild of Landlords survey of 20 lenders, reported in August 2023, showed fees from 3% up to 7% on some buy-to-let products. On a £150,000 loan that ranged from £4,500 to £10,500. Those are older figures, so treat them as an illustration of the spread and check today’s product sheets.
The lesson for your bookkeeping is simple. A fee quoted as a percentage of a large loan can easily be the biggest single finance cost in the first year. It deserves proper treatment, not a quick posting to a general expense code.
Accounting treatment and Corporation Tax are two questions
Owners often ask one question: “Can I claim it?” I split it in two.
- How does the cost go through the accounts? This is an accounting question. It depends on the accounting framework the company uses, the terms of the loan and the size of the cost.
- When does the company get tax relief? This is a Corporation Tax question. It depends on the loan relationship rules.
For a company, HMRC’s Corporate Finance Manual says that expenses fall within the loan relationship rules when they are incurred in bringing a loan relationship into existence. It gives arrangement fees with banks as an example. So the arrangement fee is generally within the scope of the rules. The decisive question is whether the fee was incurred under or for the purposes of the company’s loan relationships, and whether it relates directly to that loan.
The tax computation then generally follows the accounts. HMRC’s guidance on amortised cost accounting says the loan liability is shown at amortised cost using the effective interest rate method. It also says the carrying value reflects the amortisation of fees for entering into the loan.
In plain English: if your accounts spread the fee over the loan, the tax deduction normally follows that spread. It does not normally arrive in one lump in the year you paid it. I never assume this, though. I check the framework the accounts are prepared under and what the loan terms say.
When a fee needs spreading over the loan term
The idea is simple. If you pay £3,750 to get a five-year loan, the benefit of that cost lasts for the five years. Putting the whole amount in year one would make year one look worse than it is and later years look better.
Under the amortised cost approach, the loan starts in the accounts at the amount borrowed less the costs of getting it. Each year, part of those costs is added back to the finance charge, until the loan sits at the full amount owed at the end of the term. HMRC describes this approach in its guidance, linked above.
A few points I weigh up:
- Size of the fee. A very small fee may be expensed straight away on a practical basis if spreading it would make no real difference. For larger fees, spreading is the better picture.
- Type of loan. Interest-only, repayment and fixed-term deals all change the pattern. A shorter initial deal followed by a lender’s standard rate affects the period I choose.
- Likely early repayment. If the company plans to refinance when the fixed rate ends, the period over which I spread the cost should reflect that expectation, not just the full mortgage term.
- Accounting framework. Different frameworks have different rules on how far this applies. I confirm which one the company is using before I post anything.
I would rather agree this with the director at the start than correct it at year end.
A worked example: Harbour Lane Properties Ltd
This is a fictional company with invented figures, to show the method. It is not a real client, and the numbers are not a recommendation.
Harbour Lane Properties Ltd buys a two-bedroom flat for £250,000. It borrows £187,500 (75%) on a five-year fixed deal and draws the loan on completion. The costs connected with the mortgage are:
| Item | Amount |
|---|---|
| Lender arrangement fee (2% of £187,500) | £3,750 |
| Broker fee | £495 |
| Lender’s valuation fee | £450 |
| Total cost of the loan | £4,695 |
The survey the company commissioned for its own purposes and the conveyancing fees for the purchase are not in this table. They relate to buying the property, so they sit with the property’s cost.
How I would record it
The lender deducts the £3,750 fee from the advance at completion, and the company pays the broker and valuer separately. The loan is still £187,500 as far as the company owes. In the books I would:
- Record the loan at £187,500.
- Hold the £4,695 of loan costs against it, so the loan sits at £182,805 on day one.
- Release the costs into the finance charge over the period I have agreed, using the effective interest method if the framework requires it.
On a simple straight-line view over five years, that is about £939 a year. The effective interest method gives slightly different yearly figures, because it ties the release to the loan balance and interest rate. The total is the same: £4,695.
What changes if the fee is added to the loan
Suppose instead the lender adds the £3,750 to the loan. The company then owes £191,250, and interest runs on the full amount. The accounting is similar, but the loan balance in the lender’s statements no longer matches the amount the company actually received. That is why I always compare the loan balance with the completion statement. If I did not, the company would look as if it had borrowed more cash than it had.
What this means for tax
As the loan costs are released into the finance charge each year, the Corporation Tax computation generally follows. The amount in the first year’s accounts, not the cash paid at completion, is what usually goes into the tax return. If Harbour Lane refinances early, the unamortised balance has to be dealt with at that point. That is another reason I keep a schedule of the costs.
Paying upfront or adding the fee to the mortgage
Lenders often give two options. Moneyhelpdesk explains that you can settle the fee upfront or add it to the mortgage, and that adding it means paying more overall, because the amount borrowed and the interest both go up. The Guild of Landlords article makes the same point and describes adding the fee as more expensive.
I do not choose the mortgage for you. I am not a mortgage adviser, and that choice sits with you and your broker. What I can do is show the accounting effect of each option, so the numbers are clear before you commit:
- Fee paid upfront: the cash leaves the company at completion. The loan balance equals the amount advanced.
- Fee added to the loan: no extra cash goes out at completion, but the loan is larger and the finance charge is higher.
Either way, the fee is a cost of the loan, and I treat it consistently.
Company or individual: the rules are different
This is a trap for directors who also own property personally. HMRC’s Property Income Manual says that for individuals, the incidental costs of obtaining loan finance can be deductible when they relate wholly and exclusively to letting non-residential property. If the customer is a company, those costs fall under the loan relationship rules instead.
So you cannot take a rule you read about personal landlords and apply it to your company. The route to relief, the timing and the paperwork all differ. If you hold property both ways, my guides to rental income tax and residential landlord tax cover the personal side, and the Corporation Tax guide for limited companies covers the company side.
If the mortgage never completes
Sometimes a deal falls through after fees have been paid. Whether the money comes back depends on the lender’s terms. Moneyhelpdesk notes that arrangement fees are usually non-refundable after completion. Lenders may consider a refund if an application breaks down or you decide not to proceed before completion, depending on their terms and the reason.
For tax, HMRC’s loan relationship guidance says expenses can be taken into account even if incurred before the company became a party to the loan. The same applies where the company fails to become a party, provided they otherwise meet the requirements. I do not assume an abandoned fee qualifies. I look at what the fee was for, who paid it, and whether it truly relates to a loan the company meant to take out.
How I review mortgage agreements, completion statements and loan balances
When a property company tells me it has taken a new mortgage, I work through the same short list.
- The mortgage offer. I read the loan amount, term, rate type, fee amount, whether the fee is added to the loan, and any early repayment charges.
- The completion statement from the solicitor. This shows what actually moved on the day: the advance, the fee deducted, legal costs, stamp duty and the balance paid to the seller. I match each line to a bank transaction.
- Invoices from the broker and valuer. I check what each fee covers, and I look for any proc fee arrangement that the broker has disclosed.
- The lender’s first loan statement. The opening balance should agree to what I expect. If the fee was added to the loan, it should show here.
- A schedule of loan costs. I set up a simple schedule: total costs, the period, the yearly release and the balance still to release. I update it if the company refinances or repays early.
- Year-end loan balance. At each year end I agree the loan balance to the lender’s statement and make sure the release of costs is posted.
- Tax computation. I carry the finance charge into the Corporation Tax computation and note any adjustments.
This work sits naturally alongside my bookkeeping services. It is much easier to record the fee correctly in the month it happens than to untangle it from a year of general expenses. If your records are already behind, my bookkeeping clean-up checklist shows how I reconcile first and flag queries after.
Common mistakes I see
- Posting the fee to “bank charges” or “professional fees”. It then gets lost among everyday costs and never spread.
- Mixing property costs and loan costs. Survey and purchase legal fees are not loan costs, so they should not be treated as such.
- Forgetting that a fee was added to the loan. The loan balance then does not agree with the cash received.
- Ignoring the refinance. If the deal ends early, the unreleased costs need dealing with.
- Treating the fee as a repair or improvement. It is neither. If you are unsure where a property cost belongs, see my repairs versus capital improvements checklist.
- Assuming personal landlord rules apply to the company. They do not, as covered above.
My own view on loan costs
I think this is one of the most overlooked areas in small property company accounts. A director sees one fee on a completion statement and expects one line in the books. In reality that fee touches the loan balance, the finance charge, the tax computation and sometimes a later refinance.
When I look after a property company, I like to deal with this on the day the mortgage completes, not months later. I read the offer, match the completion statement to the bank, set up a simple schedule and agree it with you in plain English. You see how the fee affects your profit this year and next, and nothing comes as a surprise at year end.
I do not give mortgage advice, and I will not promise a particular tax result. What I can do is make sure the records are accurate, the treatment is consistent and the evidence is ready if HMRC asks.
Chris
How I can help with your property company’s records
If your company has taken out or refinanced a mortgage, I can review the offer and completion statement, set up the loan cost schedule and make sure the figures flow correctly into your accounts and Corporation Tax return. I work with limited company directors across Tonbridge, Hildenborough, Sevenoaks and the rest of Kent, and remotely across the UK. You deal with me directly, and I explain things without unnecessary jargon.
You can see how I support landlords and property owners on my rental reporting and bookkeeping page. For the company accounts and tax side, take a look at my accounting services. My fees are tailored to the work involved and agreed clearly upfront.
FAQ
Are mortgage arrangement fees tax deductible for a property company?
Generally they fall within the loan relationship rules, because HMRC’s guidance treats arrangement fees as expenses of bringing a loan into existence. The deduction usually follows how the fee is treated in the accounts, so it is often spread over the loan term. Your facts matter, so check your own position with an accountant.
Do I record the fee as an expense or against the loan?
Often it is held against the loan and released over the term, especially where the fee is large. A small fee may sometimes be expensed straight away on a practical basis. The right answer depends on the accounting framework your company uses and the size of the fee.
What if the lender adds the arrangement fee to the loan?
Then the loan balance is higher than the cash you received, and interest is charged on the fee. NatWest confirms that interest is payable where the fee is added. I match the lender’s statement to the completion statement so the difference is clear in your books.
Are broker fees and valuation fees treated the same way as the arrangement fee?
Often they are dealt with together, if they are costs of obtaining the loan. A lender’s valuation is usually a cost of the loan. Your own survey for buying the property is usually part of the property’s cost. I check what each invoice covers before I decide.
Does the same treatment apply if I own the property personally?
No. For individuals, HMRC’s property income guidance applies, and different conditions apply. If you are a director who also owns property personally, I keep the two separate.
Need help?
If you would like me to look at your property company’s mortgage costs, please get in touch. Tell me a little about the company and the loan, and I will explain how I can help. I will not promise outcomes, but I will make the process calm and clear.
Sources
- Understanding Arrangement Fees, NatWest Business
- Residential property investment loan, NatWest Business
- The Mortgage Works expands limited company range, Nationwide
- Commercial mortgage price list, Atom bank
- Unmasking the True Cost of Buy-to-Let Mortgage Fees, Guild of Landlords
- What is a Mortgage Arrangement Fee?, Moneyhelpdesk
- CFM33060 Loan relationships: core rules: expenses, HMRC
- CFM33100 Loan relationships: GAAP, fair value and amortised cost, HMRC
- PIM2105 Fees for loan finance, HMRC
Recommended
- How to Account for Property Purchases in a Limited Company
- UK landlords: mortgage interest tax credit explained with examples
- HMO landlord tax obligations explained: your 2026 guide
- Residential landlord tax explained: 2026 UK guide
This article provides general information based on UK tax and accounting rules at the time of publication. It is not a substitute for advice tailored to your individual circumstances. Tax legislation and HMRC guidance may change. If you need advice about your specific situation, please contact me at CW Licensed Bookkeeper & Accountant.