Every limited company director must record sales and purchase invoices, receipts, bank transactions, payroll and VAT paperwork, fixed assets, and director’s loan account movements, keeping those records for at least the minimum period required by HMRC. The first practical step is opening a dedicated business bank account and starting monthly reconciliations, because that single habit catches most errors before they become expensive.
TL;DR:
- Keeping digital copies of invoices, receipts, and bank statements for six years is acceptable and ensures compliance with HMRC and Companies House requirements.
- Opening a dedicated business bank account before trading and reconciling it monthly helps prevent errors and keeps financial records accurate.
- Recording every director-paid expense with a receipt and regularly reconciling the director’s loan account avoids tax risks and potential disqualification.
- Regularly reviewing bank feed transactions for duplicates or categorization errors reduces reconciliation issues and maintains data integrity.
- Precise record-keeping of assets, loans, and dividends with proper documentation is essential for accurate statutory accounts and tax compliance.
Table of Contents
- What records does bookkeeping for a limited company require?
- Keep company and personal money separate
- How do you record day-to-day transactions accurately?
- What VAT and payroll records affect your bookkeeping?
- How should you record assets, loans and dividends?
- Cloud accounting and bank feeds: useful, not infallible
- How does bookkeeping feed your statutory accounts?
- A monthly bookkeeping checklist for directors
- Why I built my practice around clean, current records
- Get your bookkeeping properly organised
- Sources
- FAQ
What records does bookkeeping for a limited company require?
Companies Act 2006 requires every company to keep accounting records that show and explain its transactions and disclose its financial position with reasonable accuracy. That is a broad legal duty, but in practice it breaks down into specific documents you need on file.
- Sales invoices raised to customers, showing date, amount, VAT (if registered) and what was supplied
- Purchase invoices and receipts for anything the company buys, including small expenses
- Bank statements for every business account, plus records of cash transactions
- Payroll records if you employ staff or pay yourself a salary through PAYE
- VAT records if you’re registered, covering both output and input VAT
- A fixed asset register for equipment, vehicles and other capital purchases
- Records of director’s loan account movements and stock records where relevant
On retention, there’s a genuine mismatch in the rules that catches directors out. The Companies Act sets a three-year minimum for private companies, but HMRC’s tax rules require six years from the end of the accounting period they relate to. Six years is the number that actually governs most limited companies, because tax compliance almost always outlasts the company law minimum. My guide on how long to keep tax records sets out the detail if you want the full breakdown by document type.
On storage, digital copies are perfectly acceptable to both Companies House and HMRC, provided they’re legible and complete. A photographed receipt filed in cloud software counts, as long as you can still read it in six years’ time.
Keep company and personal money separate
A limited company is a separate legal entity from you. Its money is not your money, even if you’re the only shareholder and director, and treating the business bank account like a personal account is one of the fastest ways to create a bookkeeping mess.
That’s where the director’s loan account comes in. It tracks money the company owes you, or money you owe the company. If you pay a business expense from your own pocket, that’s typically recorded as a credit to your director’s loan account rather than left unrecorded, and GOV.UK guidance is clear that you need supporting receipts to back the entry. Miss that step and the company risks losing a legitimate deduction, or getting the tax treatment wrong entirely.
- Open a dedicated business account before you trade, not after your first invoice
- Record every director-paid expense with a receipt, even small ones like parking or stationery
- Reconcile the director’s loan account monthly, not once a year at accounts time
- Never treat company funds as available for personal spending without a formal dividend or salary route
Pro Tip: An overdrawn director’s loan account (where you owe the company money) can trigger a Corporation Tax charge under section 455 if it’s not cleared within nine months of the year end, on top of possible benefit-in-kind implications. Watch the balance, not just the transactions.
Persistent commingling of funds, or accounting records too poor to show what happened to company money, is exactly the kind of failure that can lead to director disqualification in serious cases. That’s a rare outcome, but it starts with exactly this kind of sloppy record keeping.
How do you record day-to-day transactions accurately?
Good bookkeeping is a routine, not a scramble before a deadline. Break it into three habits and most of the year-end pain disappears.
- Raise sales invoices properly. Every invoice needs a unique number, the date, your company details, a clear description of what was supplied, the net amount, VAT if applicable, and the total due. Missing fields cause disputes and slow down payment.
- Record purchase invoices as they arrive. Log the supplier, date, amount, and what it was for, and keep the source document, whether that’s a PDF invoice or a scanned till receipt. Don’t rely on memory or a bank line description months later.
- Reconcile the bank account regularly. Match every line on your bank statement to an invoice, receipt or payroll entry. Weekly is ideal for an active trading company; monthly is the outer limit before errors start compounding.
A small team can split this sensibly: whoever raises invoices does so the same day the work is done, someone (often the director) approves and pays supplier invoices weekly, and reconciliation happens on a fixed day each month, not “whenever there’s time.” Cloud accounting software with a live bank feed removes most of the manual entry, but the feed only tells you what happened, not what it was for. You still have to categorise it correctly.
Pro Tip: Set a recurring calendar reminder for bank reconciliation, the same way you’d remind yourself about a VAT deadline. Bookkeeping that depends on remembering to do it eventually doesn’t get done.
Sloppy invoice records don’t just cause admin headaches. They obscure how the business is actually performing, because you can’t trust a profit figure built on incomplete data.
What VAT and payroll records affect your bookkeeping?
If you’re VAT registered, you need records of output VAT (charged on sales) and input VAT (reclaimed on purchases), with each invoice showing the VAT amount separately. Your bookkeeping software should post these to distinct VAT control accounts, not lump them into general sales and purchases, otherwise your VAT return calculation becomes guesswork rather than a report pulled straight from clean data.
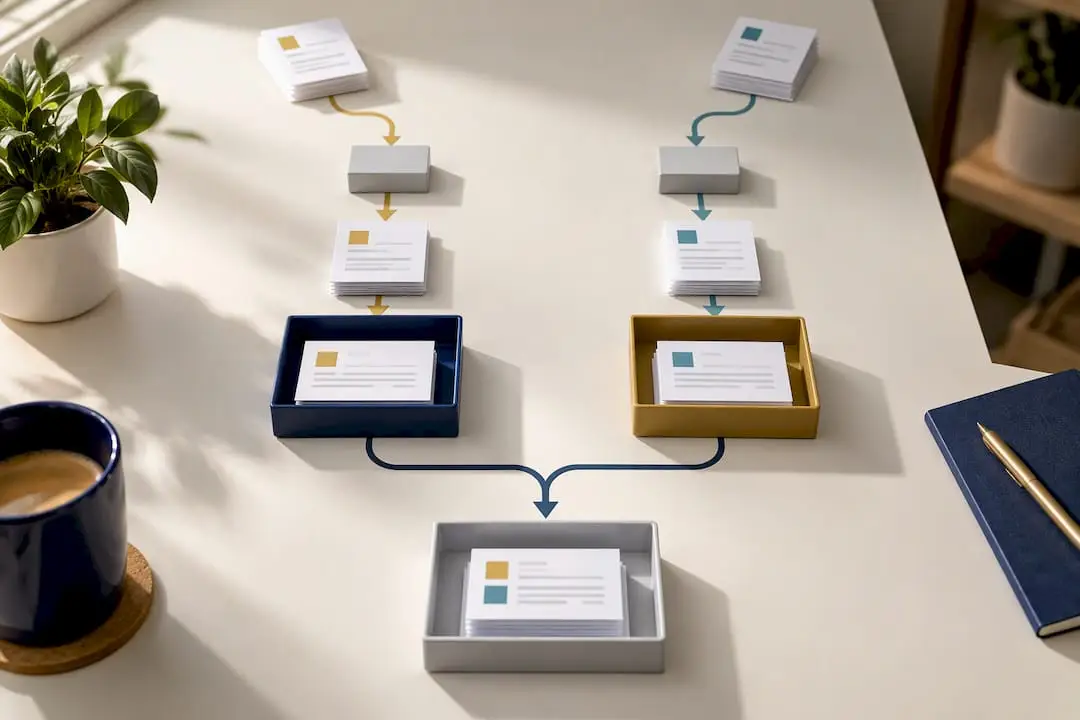
Watch the VAT registration threshold even before you’re required to register. If turnover is climbing towards the threshold, review your bookkeeping monthly rather than waiting for your accountant to flag it at year end, because registering late carries its own penalties.
Payroll adds another layer of record keeping if you employ staff or pay yourself through PAYE:
- Payment records for each employee, including gross pay, deductions and net pay
- Real Time Information (RTI) submissions made to HMRC each pay period
- P60s, P45s and any benefit-in-kind records
- Employer’s National Insurance calculations and payment evidence
Payroll entries should post into the company accounts as a liability until paid, then clear against the bank payment, rather than being recorded as a single lump expense with no breakdown. My VAT return guide covers the mechanics of the return itself if you want a fuller walkthrough of common filing errors.
How should you record assets, loans and dividends?
Capital purchases, company loans and dividends all need their own paper trail, distinct from routine trading transactions, because HMRC and Companies House both expect to see how these figures were arrived at.
A fixed asset register should record the description, cost, purchase date, expected useful life and depreciation method for every significant asset, from a company van to a laptop bought for a new starter. This matters because capital expenditure (an asset that lasts beyond a year) is treated differently in the accounts from revenue expenditure (day-to-day running costs), and getting that split wrong distorts your profit figure.
- Log the loan agreement, drawdown date and repayment schedule for any company borrowing
- Split each repayment between capital and interest, since only the interest is a cost to the business
- Record dividends only after a formal board resolution, with the date, amount per share and total documented
- File dividend paperwork even for a single-director company, because HMRC can and does ask for it
Dividends paid without proper documentation, or paid when the company doesn’t actually have sufficient distributable profits, create real tax risk further down the line.
Cloud accounting and bank feeds: useful, not infallible
Cloud bookkeeping platforms with live bank feeds cut out huge amounts of manual data entry, and remote access means you or your bookkeeper can review the books from anywhere rather than waiting for a monthly export. That’s a genuine benefit for a small limited company where the director is often juggling bookkeeping alongside actually running the business.
But automation makes mistakes with a confidence that manual entry never had. A bank feed rule can easily mark a director’s loan repayment as a general expense, or duplicate a payment that was entered twice, once by the feed and once manually. Left unchecked, these errors get reconciled straight into your accounts and become genuinely difficult to unpick months later.
- Review uncoded or “unreviewed” bank feed items at least weekly
- Check for duplicated entries, particularly around supplier payments and loan movements
- Query anything the software has categorised automatically that looks unusual
- Reconcile bank balances against statements monthly, not just when the feed says everything matches
Pro Tip: Set up bank feed rules cautiously, and have a bookkeeper review them when they’re first created. A rule that miscategorises one transaction type will keep making the same mistake every month until someone catches it.
For setup and training on platforms like Xero, QuickBooks or FreeAgent, my accounting software setup service in Kent covers exactly this kind of configuration.
How does bookkeeping feed your statutory accounts?
Your year-end profit and loss account, balance sheet and Corporation Tax return are built entirely from the numbers your bookkeeping has already generated. GOV.UK’s guidance on preparing accounts sets out what those statutory accounts need to contain, but the raw material comes from the invoices, bank entries and payroll records logged throughout the year.
- Reconciled bank accounts become the cash figures on your balance sheet
- Categorised income and expenses become the lines on your profit and loss account
- The fixed asset register and depreciation entries become your balance sheet asset values
- The director’s loan account balance appears directly as a debtor or creditor
When those figures are wrong or incomplete, your accountant has to spend time reconstructing them at year end, which increases fees and delays filing. Worse, an unexpected Corporation Tax bill often traces straight back to a director’s loan account that wasn’t reconciled all year, or expenses that were never properly categorised. Keeping the books current, month by month, is what makes year-end straightforward rather than a scramble. My piece on avoiding common Corporation Tax filing mistakes covers the specific errors that poor bookkeeping tends to produce.
A monthly bookkeeping checklist for directors
Hand this to whoever is responsible for bookkeeping, whether that’s you or an outsourced bookkeeper, and make it someone’s named job rather than a general intention.
- Weekly: review the bank feed, code any uncoded transactions, and flag anything unusual for the director to check.
- Monthly: post all outstanding sales and purchase invoices, reconcile supplier and customer ledgers, and check the director’s loan account balance.
- Monthly: review VAT and payroll liabilities to confirm they match what’s actually owed, not just what the software calculated.
- Quarterly: prepare and submit VAT returns where registered, and run a provisional Corporation Tax estimate so there are no surprises.
- Annually: pull together the full-year records for statutory accounts, checking the fixed asset register and dividend paperwork are complete.
Assign each task to a specific person and a specific day. A checklist nobody owns doesn’t get done.
Why I built my practice around clean, current records
I’m AAT-licensed and run a paperless, cloud-based practice, because I’ve seen how much stress comes from records that only get looked at once a year. Clients get bookkeeping that’s genuinely HMRC-ready year-round, not reconstructed under pressure in March.
If reconciliations are slipping, the director’s loan account is a mystery, or VAT deadlines keep arriving as a surprise, that’s usually the point to call a bookkeeper rather than keep patching things together yourself.
— Chris
Get your bookkeeping properly organised
I offer paperless, technology-led bookkeeping using popular cloud accounting platforms, with pricing agreed clearly upfront before any work starts.
I handle the bookkeeping services that keep your records current month to month, alongside VAT registration and returns, payroll, CIS and Corporation Tax support when you need the fuller picture covered. If you’re still running things on Excel or a shoebox of receipts, I also offer accounting software setup and training to get Xero, QuickBooks or FreeAgent working properly from day one. For record retention that touches business mileage and travel expenses, this grey fleet management checklist is a useful reference for what evidence to keep.
Clients deal directly with me, not a call centre, and get practical explanations without jargon. If your bookkeeping needs sorting before your next VAT return or year end catches you out, get in touch and I’ll tell you plainly what needs doing.
Sources
FAQ
How much does a bookkeeper cost in the UK?
Costs vary widely depending on the complexity of the company and the volume of transactions, so most bookkeepers, including CWABC, agree a fixed fee upfront rather than a flat hourly rate. Current pricing for CWABC’s bookkeeping services is available on request via the bookkeeping services page.
Do you need a licence to be a bookkeeper in the UK?
There’s no single mandatory licence to work as a bookkeeper, but reputable practitioners hold a recognised qualification and supervision, such as AAT licensing, which covers anti-money laundering compliance and professional standards. Always check a bookkeeper’s credentials before handing over financial records.
What’s the best accounting software for a small limited company?
Xero, QuickBooks and FreeAgent are the three most widely used cloud platforms for UK limited companies, each offering live bank feeds, invoicing and Making Tax Digital compatibility. The right choice depends on your business size, whether you need payroll built in, and how you like to work, which is why proper setup and training matters more than the brand name.
What are HMRC’s record-keeping requirements for a limited company?
HMRC requires companies to keep records that show and explain all transactions, including invoices, receipts, bank statements, payroll and VAT records, for six years from the end of the accounting period they relate to. This differs from the Companies Act’s three-year minimum for private companies, but the six-year HMRC rule is the one that governs practical retention for tax purposes.